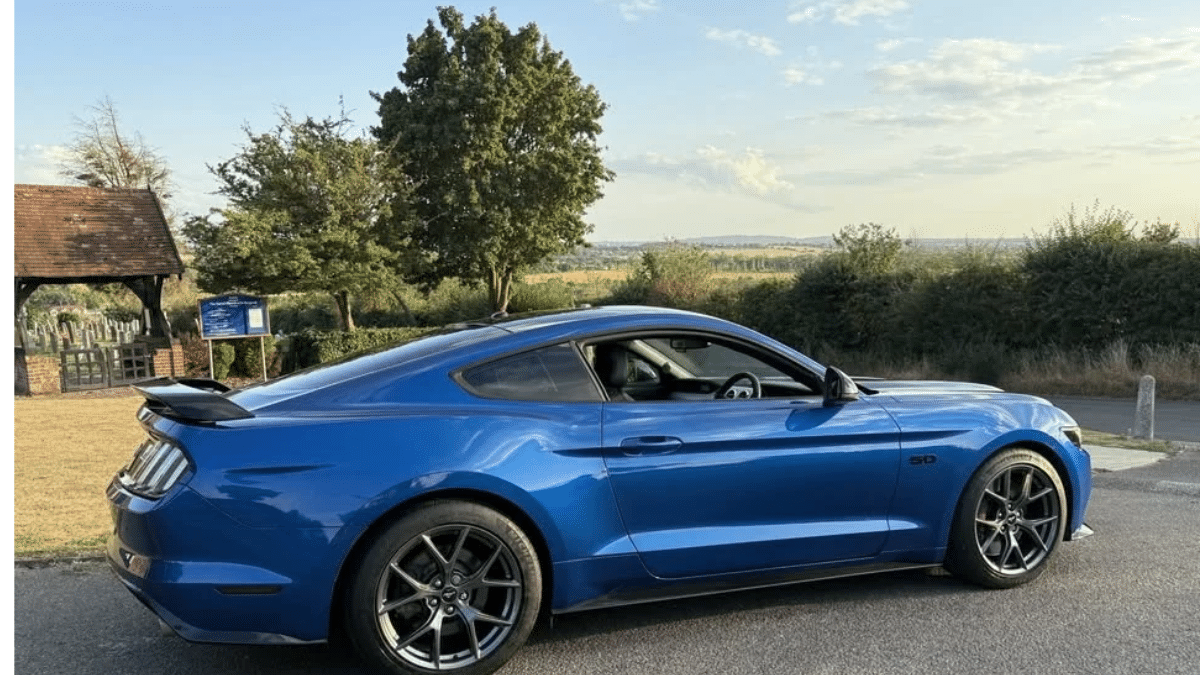
Securing the best ford mustang finance deals is the smartest way to own a legendary muscle car without emptying your cash reserves. Whether you intend to purchase the 5.0-litre Coyote V8 or the turbocharged 2.3-litre EcoBoost, using structured automotive credit protects your personal capital and spreads showroom costs across predictable monthly payments.
Shopping for ford mustang car finance in the UK requires a clear comparison between Personal Contract Purchase (PCP), traditional Hire Purchase (HP), and seasonal manufacturer promotions. Understanding loan amortization, residual balloon calculations, and underwriting criteria will help you negotiate the best deal possible.
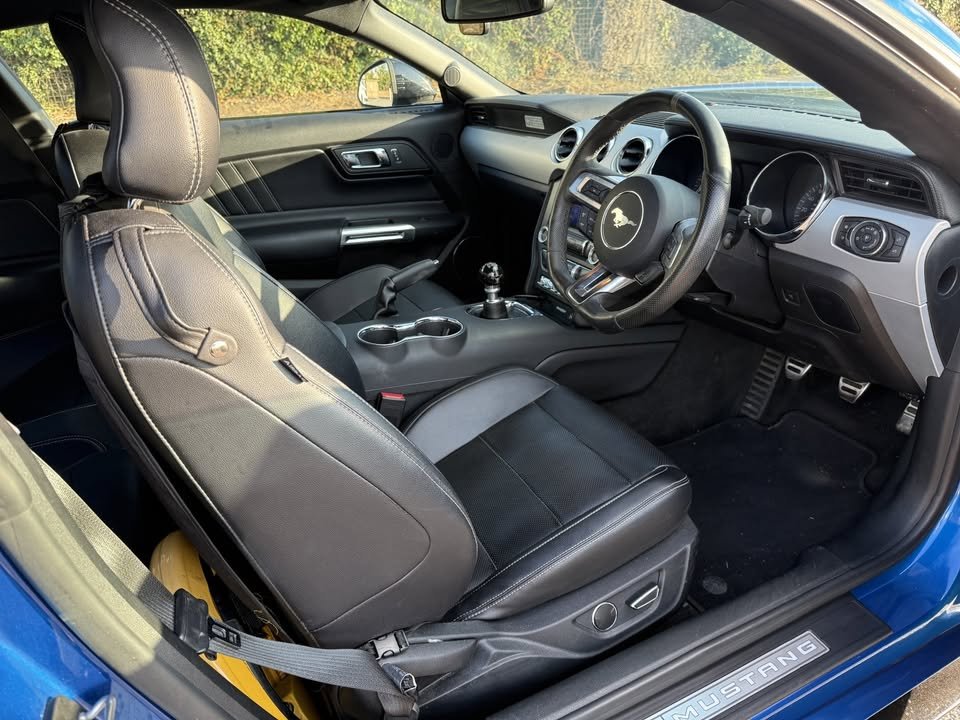
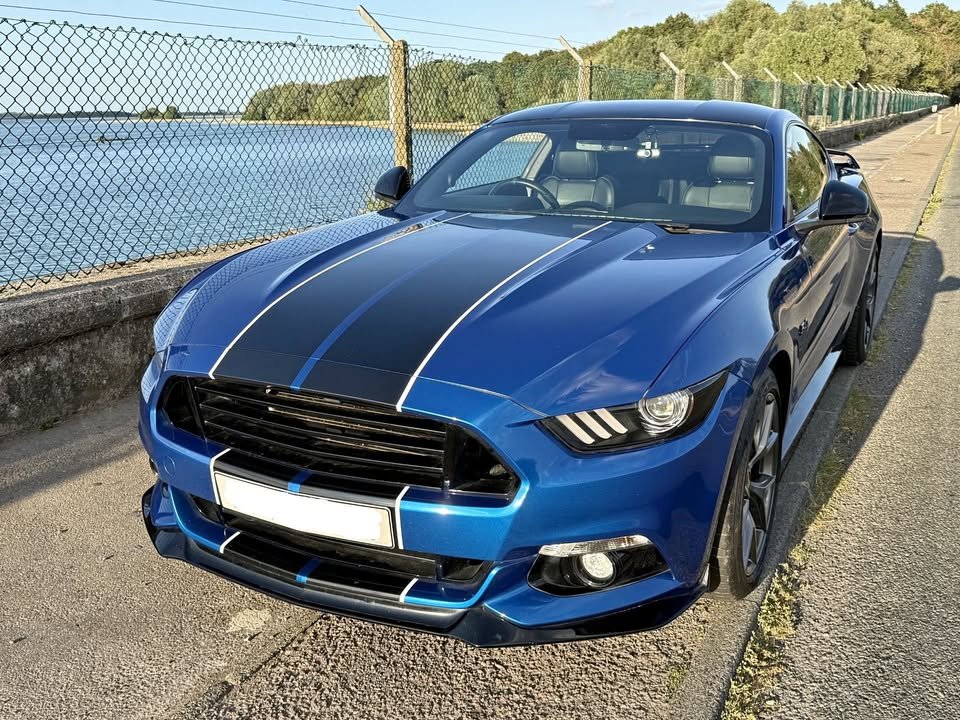
ford mustang finance deals showroom vehicle prepared for handover
Mastering Ford Mustang PCP Agreements
Personal Contract Purchase remains the most widely selected finance method for private sports car buyers across the UK. A ford mustang pcp agreement structures your borrowing into three distinct elements: your upfront deposit, fixed monthly repayments, and a deferred balloon payment known as the Guaranteed Minimum Future Value (GMFV).
+-------------------------------------------------------------+
|               HOW PCP MONTHLY PAYMENTS ARE FORMED           |
|                                                             |
|  [ Vehicle Price ] - [ Customer Deposit ] - [ GMFV Value ]  |
|                                                             |
|   = Financed Balance / Term Length (Plus Interest Charges)  |
+-------------------------------------------------------------+
Because your monthly payments only service the anticipated depreciation over 24, 36, or 48 months rather than the car’s complete retail value, PCP monthly payments remain significantly lower than standard personal loans.
When your term ends, you retain three flexible paths:
- Pay the GMFV Balloon: Settle the optional final payment and title transfer fee to take outright ownership of the vehicle.
- Part-Exchange with Retained Equity: If current market values exceed the pre-agreed GMFV figure, apply that positive cash margin as a deposit toward your next car.
- Return the Keys: Hand the Mustang back to the lender with zero liability, provided you stay within agreed mileage caps and meet standard return conditions.
Evaluating Factory Subsidies and Ford Mustang Offers
Manufacturer finance subsidiaries such as Ford Credit regularly launch competitive ford mustang offers to stimulate showroom activity. Taking advantage of these dealer network campaigns can save you thousands compared to third-party high street loans.
- Deposit Contribution Allowances: Manufacturers frequently contribute between £1,000 and £3,500 toward your deposit when you take out finance through their designated lenders.
- Subsidised Promotional APR: High street auto lenders often charge 9.9% to 12.9% APR on used performance cars. Official seasonal campaigns frequently discount APR down to 2.9% to 5.9%, dramatically reducing interest charges.
- Complimentary Servicing Plans: Many promotional campaigns package the vehicle’s first two or three scheduled main-dealer service intervals into the contract.
When reviewing showroom offers, always examine the Total Amount Payable rather than focusing solely on the monthly installment. A higher upfront deposit paired with a sub-4% APR rate will usually beat a zero-deposit plan burdened with double-digit borrowing interest.
For regulatory guidelines governing vehicle credit agreements and consumer protection rules, review the official Financial Conduct Authority Credit Regulations.
PCP vs. Hire Purchase (HP): Which Route Suits You?
Deciding between PCP and HP comes down to whether you prioritize vehicle ownership or lower monthly outgoings.
| Finance Attribute | Personal Contract Purchase (PCP) | Hire Purchase (HP) |
| Primary Goal | Flexibility and lower monthly bills | Full, unencumbered ownership |
| Monthly Cost | Low to moderate | Moderate to high |
| Final Balloon | Yes (Optional GMFV payment) | No final balloon (Zero balance) |
| Mileage Limits | Yes (Excess penalties apply) | No mileage restrictions |
| Early Termination | Voluntary termination rules apply | Voluntary termination rules apply |
If you plan to keep the car for a decade or more and modify the exhaust and suspension, traditional Hire Purchase avoids end-of-term return clauses and mileage limitations.
However, if you like upgrading to newer models every three years, PCP provides predictable depreciation protection.
Underwriting Rules and Credit Score Optimization
Lenders enforce strict affordability criteria before issuing credit on high-performance sports cars. Passing credit underwriting on your first attempt requires keeping these key factors in mind:
- Debt-to-Income (DTI) Ratios: Underwriters verify your net monthly income against existing credit obligations. As a rule of thumb, total vehicle finance repayments should not exceed 20% of your verifiable take-home pay.
- Voters Roll Registration: Lenders cross-reference your residential address through the electoral register. Having an unverified address history is one of the quickest ways to receive an automatic credit rejection.
- Soft Search Quotes: Always request a soft credit check before applying formally. Soft searches show your likelihood of acceptance and preliminary APR tiers without leaving an inquiry mark on your public credit report.
Before finalizing terms, check our breakdown on Ford Mustang Running and Maintenance Costs and review our Mustang Reliability and Inspection Guide to build an accurate monthly ownership budget.
4 Actionable Tips to Cut Your Monthly Finance Payments
To lock down the most cost-effective ford mustang finance deals, implement these practical finance tips:
- Increase Your Upfront Deposit: Raising your initial cash deposit from 10% to 20% reduces the borrowed principal, directly cutting your total interest charges.
- Set Accurate Annual Mileage Caps: Choosing an accurate 8,000-mile limit instead of a generic 12,000-mile figure protects the car’s projected residual value (GMFV), which lowers your monthly payments.
- Consider Approved Used Stock: Financing a certified pre-owned 2-to-3-year-old Mustang lets the original buyer absorb the steep initial depreciation while keeping the vehicle eligible for competitive dealer finance.
- Source GAP Insurance Independently: Protect your investment against total-loss write-offs with standalone Guaranteed Asset Protection (GAP) insurance. Independent online brokers typically charge 60% less for GAP cover than dealership finance managers.
Frequently Asked Questions
Can I end my Ford Mustang PCP contract early?
Yes. Under the UK Consumer Credit Act, you can request an official early settlement figure from your finance provider at any point. If the vehicle’s market value exceeds this figure, you can sell or trade in the car, settle the loan balance, and pocket any surplus equity.
What happens if I go over my agreed PCP mileage?
If you return the car at the end of the term, you will be charged an excess mileage fee (typically 8p to 18p plus VAT per excess mile). However, if you choose to pay the optional balloon payment to keep the vehicle or trade it in, excess mileage charges do not apply.
Do I need a deposit for Ford Mustang car finance?
Zero-deposit finance agreements are widely available for applicants with strong credit ratings. However, putting down at least 10% reduces monthly payments and lowers the risk of ending up in negative equity during the first two years of the agreement.